Repo Rate at 5.50%: The Smart Siliguri Homebuyer’s Playbook to Protect Your EMI and Still Buy Right in 2026
GFS Realtors
We provide deep market insights and strategic advice for real estate buyers, sellers, and investors.
Expert at providing deep market insights and strategic advice for real estate
Repo Rate at 5.50%: The Smart Siliguri Homebuyer’s Playbook to Protect Your EMI and Still Buy Right in 2026
Direct answer: The RBI raised the repo rate by 25 basis points to 5.50% on 7 October 2026 — its first hike in over 3.5 years. If you’re buying or repaying a home in Siliguri, the useful question isn’t “should I worry?” — it’s “what do I actually do now?” The honest answer: a 25 bps move adds roughly ₹800 a month to a ₹50 lakh home loan — real, but manageable, and no reason to abandon a sound property decision. This is a practical playbook: how to protect your EMI, structure your loan smartly, and still buy well in Siliguri’s affordable, end-user-driven market.
The 30-Second Recap
Item | Detail |
|---|---|
Repo rate | 5.50% (up 25 bps from 5.25%) |
Date | 7 October 2026 (first hike in 3.5 years) |
Stance | Neutral → “calibrated tightening” |
FY27 inflation | 5.2% (may peak ~6% in Q3) |
FY27 GDP | Upgraded to 7.1% |
For the full breakdown of why the RBI moved, read our companion explainer How RBI Interest Rate Decisions Affect Home Buyers in Siliguri and the earlier RBI Holds Repo Rate at 5.25% (August 2026). The key context: rates rose alongside a GDP upgrade to 7.1% — a sign of economic strength, not stress.
First, Right-Size the Fear: The Real EMI Math
On a 20-year loan, if your floating rate resets from 8.50% to 8.75%:
Loan Amount | EMI at 8.50% | EMI at 8.75% | Extra per month |
|---|---|---|---|
₹30 lakh | ~₹26,033 | ~₹26,512 | ~₹479 |
₹50 lakh | ~₹43,391 | ~₹44,186 | ~₹795 |
₹75 lakh | ~₹65,083 | ~₹66,279 | ~₹1,196 |
Illustrative; your actual change depends on your lender, spread, reset date and tenure.
On a typical ₹50 lakh loan, that’s about ₹800 a month — roughly a weekend dinner out. The playbook below can offset most or all of it. For the full borrowing picture, see Home Loans in India: Complete Guide to Tax Benefits, Eligibility & Rates and, for land, How Much Loan Can You Get to Buy a Plot in India?.
The 7-Step EMI Protection Playbook
Step 1 — Negotiate the spread, not just the rate
Your home loan rate = external benchmark (linked to repo) + your lender’s spread. You can’t change the repo, but you can negotiate the spread — especially with a strong credit score and stable income. Even 15–20 bps off the spread can cancel out this hike.
Step 2 — Choose tenure reduction over EMI reduction
When your rate resets, lenders usually extend your tenure to keep the EMI flat. That quietly costs you lakhs in extra interest. If you can afford it, keep the EMI the same and let the tenure shorten — you’ll pay far less overall.
Step 3 — Make a small annual prepayment
A single modest prepayment each year (even one month’s EMI) can offset a 25 bps rise entirely, because it attacks the principal directly. Prepay early in the loan, when the interest component is highest.
Step 4 — Consider a balance transfer
If another lender offers a materially lower rate (after factoring processing fees), a balance transfer can save more than this hike costs. Compare the effective rate, not the teaser rate.
Step 5 — Weigh fixed vs floating honestly
With the stance now “calibrated tightening,” floating rates could rise further. A fixed rate offers certainty but usually starts higher. There’s no universal answer — decide on your tenure, cash flow and risk comfort. On the broader timing question, see the GFS Realtors guide When Is the Right Time to Buy a Home in 2026? (Hindi).
Step 6 — Maximise your tax shield
Home loan interest (Sec 24b) and principal (Sec 80C) deductions soften the real cost of a slightly higher EMI. Factor your post-tax EMI, not the gross number — details in our Home Loans Complete Guide.
Step 7 — Buy within your budget, not your eligibility
The oldest rule, and the most protective: borrow for the home you can comfortably repay, not the maximum the bank offers. This single discipline makes rate cycles almost irrelevant to your peace of mind. See How to Buy Your First Flat in Siliguri.
Why This Is Still a Smart Window to Buy in Siliguri
A rate hike changes your EMI by a little. It doesn’t change the fundamentals — and in Siliguri, those are unusually strong.
1. Affordability means a smaller absolute hit
A 25 bps rise on a ₹30–40 lakh Siliguri flat is far gentler than on a ₹1.5 crore metro apartment. See 2 BHK Flats in Siliguri Under ₹50 Lakh and ₹1 Crore in Real Estate: Siliguri vs Tier-2 Cities.
2. Property is an inflation hedge
In a rising-inflation phase, physical assets tend to hold value — a reason investors rotate into real estate, as explored in From Gold to Real Estate and Why Real Estate Is the Smartest Investment Amid Global Uncertainty.
3. The growth story keeps compounding
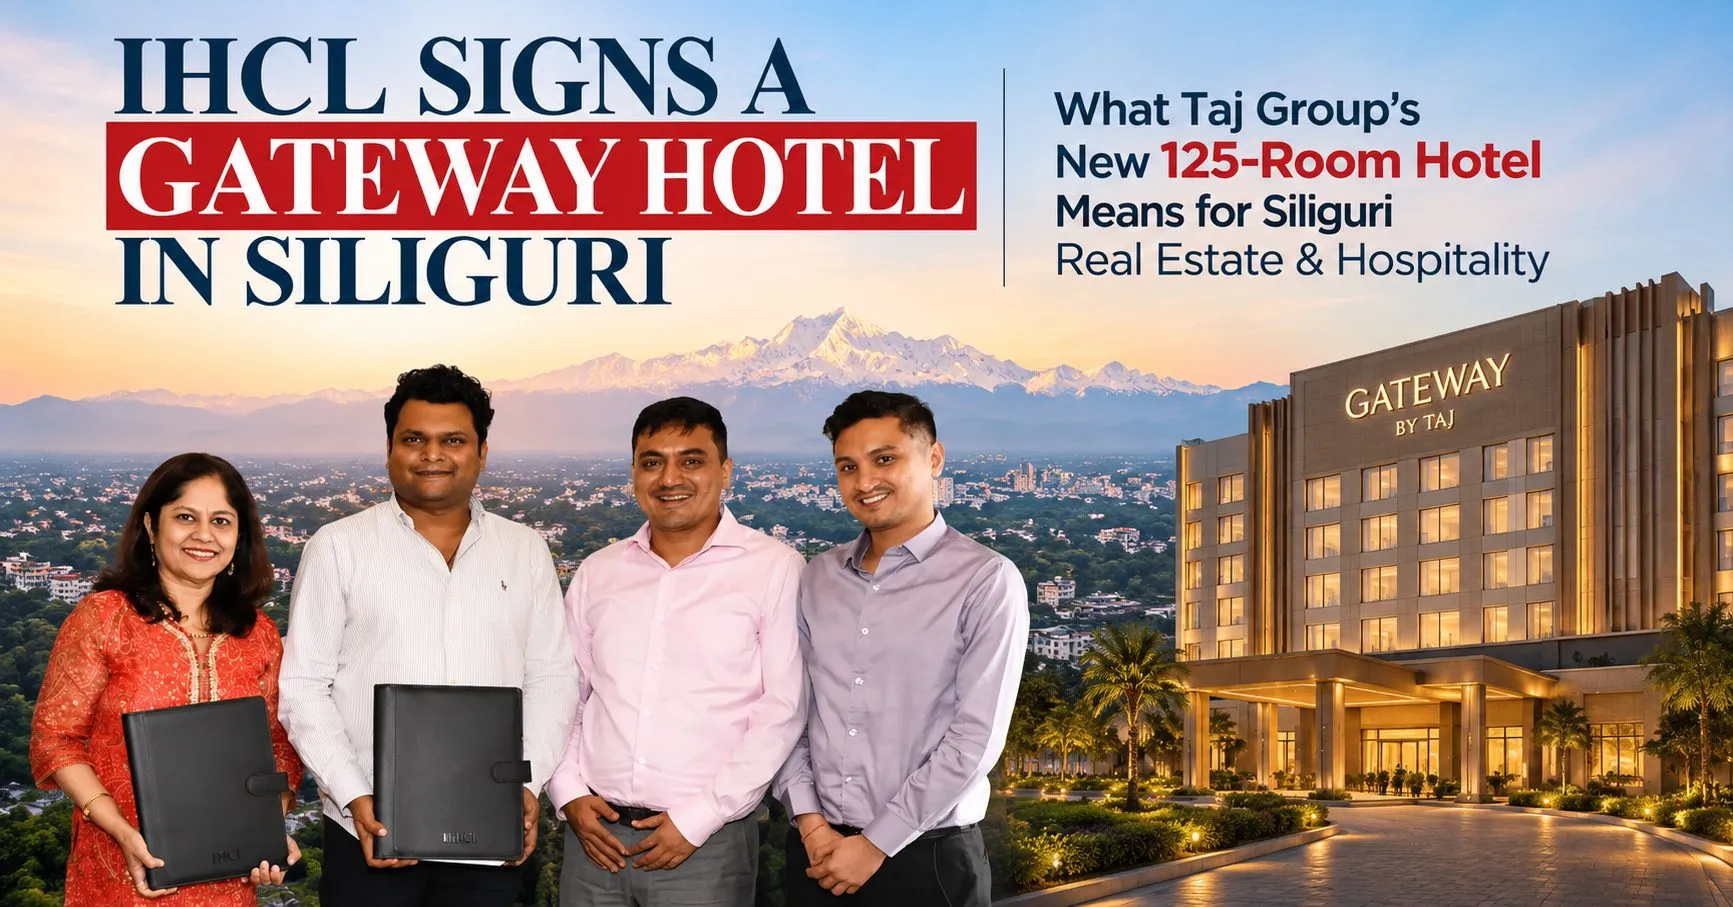
Rate cycles come and go; Siliguri’s infrastructure and investment wave keeps building — the Bagdogra terminal (1 crore passengers), the NH-10 Teesta bridge, NH-327 four-laning, branded hotels (JW Marriott, IHCL Gateway) and a large tourism pipeline. Track them in our North Bengal Infrastructure Tracker and Siliguri’s Infrastructure Revolution. Context: Why Siliguri Is North Bengal’s #1 Real Estate Investment Destination and the GFS North Bengal Real Estate 2026 Complete Guide.
4. Land & plots are largely loan-light
Much of Siliguri’s land buying uses own funds, so it’s minimally rate-sensitive — see Why Investing in Plots in Siliguri is One of the Smartest Moves and Plotted Developments from ₹15–20 Lakh.
Who Should Do What — A Quick Guide
If you are… | Your move |
|---|---|
An existing floating-rate borrower | Keep EMI flat (shorten tenure); make a small prepayment; check for a balance transfer |
A first-time buyer | Negotiate the spread; buy within budget; compare fixed vs floating |
An investor | Treat property as an inflation hedge; favour strong corridors and clean title |
A land/plot buyer | Rate impact is minimal if using own funds — focus on title and location |
A retiree / saver | Enjoy higher FD returns; pair income assets with a Siliguri home — see Why Retirees Are Choosing Siliguri |
For getting the price itself down, see the GFS Realtors guide Property Price Negotiation in Siliguri — negotiating ₹2–3 lakh off the price can dwarf the entire EMI impact of this hike.
Don’t Skip Due Diligence — It Matters More Than Rates
Clear title, mutation (Namjari), khatian (RS/LR), ULPIN
Land-use conversion and RERA — WBRERA Explained
Documents, registration, stamp duty — Documents Required, Property Registration, Stamp Duty & Registration Charges in WB
Agreement clauses — How to Read an Agreement for Sale
This is general information, not financial or legal advice. Interest-rate impact depends on your specific loan; consult your lender and a qualified advisor, and verify a property’s legal status with a professional, before deciding.
Honest Caveats
Further hikes are possible — the stance is “calibrated tightening.”
Transmission varies — your EMI change depends on your lender and reset date.
Borrow within comfort — high-leverage buyers should recheck affordability.
Rates are one factor — location, title and project quality drive outcomes far more.
What to Watch Over the Next 6–12 Months
Inflation is expected to peak near 6% in Q3 before easing toward 5.7% by Q4 FY27 — so this may be a short tightening phase, though more hikes can’t be ruled out. For Siliguri, the modest EMI impact is likely to be outweighed by strong structural tailwinds. The disciplined buyer who follows the playbook above will barely feel this cycle.
🔑 Key Takeaways
🏦 Repo rate is now 5.50% (+25 bps, 7 Oct 2026) — but it came with a GDP upgrade to 7.1%.
💸 The hit is small — ~₹800/month on a ₹50 lakh loan; the playbook can offset most of it.
🛠️ Seven levers — negotiate the spread, shorten tenure, prepay, consider a balance transfer, weigh fixed vs floating, use tax breaks, buy within budget.
🏙️ Siliguri stays resilient — affordable, end-user-driven, land often loan-light, infrastructure-rich.
🤝 Negotiating the price can save far more than this hike costs.
✅ Buy on fundamentals — verify title and location; a 25 bps move shouldn’t derail a sound decision.
👤 About the Author
Written by the Gfs Realtors Team — GFS Realtors’ hyperlocal property resource for Siliguri & North Bengal, with 20+ years of combined experience turning rate, policy and market changes into practical, on-ground decisions for buyers and investors.
📚 Related Reads (Solve Every Related Query Here)
🏡 Rates Move. A Smart Purchase Stays Smart.
A 25 bps hike is no reason to pause a sound property decision — the right home, bought within budget, with the price and loan negotiated well, beats “waiting for perfect rates” every time. That’s exactly where GFS Realtors adds value.
👉 Explore land, plots, flats & verified commercial spaces on SiliguriProperties.com — including live projects like Tulsi Vatika, Rangapani, Utsodhaara Residencia and Darpan 88, Sevoke Road.
📞 Talk to GFS Realtors — Sanat Trade Center, 1st Floor, Sevoke Road, Siliguri-01. Call +91 99320 66666. With 20+ years reading North Bengal’s market, we help buyers time their purchase, structure the loan and verify every property end-to-end before they commit. 🌐 siliguriproperties.com · gfsrealtors.com
This article is general market commentary based on the RBI’s Monetary Policy Committee decision of 7 October 2026 (repo rate raised 25 bps to 5.50%), for information only — not investment, financial or legal advice. EMI figures are illustrative and depend on your lender, loan spread, tenure and reset date. Interest rates and projections are subject to change. Always consult your lender and a qualified financial advisor, and verify a property’s legal status with a professional, before deciding.